
Finally, Some Good News for Property Investors
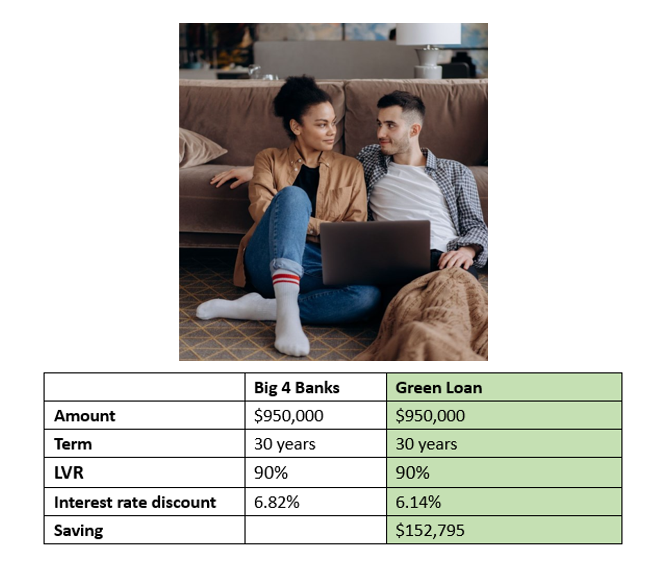
It's been a tough stretch for property investors, between negative gearing changes, CGT pressure and climbing investor rates. Here's some good news: green lending is genuinely working in your favour, and it's just as useful for refinancing a property you already hold as it is for a new purchase. If you haven't looked at your investment loan in a while, refinancing onto a green rate could be an easy win, and there's more than one way to get there.
What could get you a green loan?
Green loans aren't just for brand new, architect-designed homes. Depending on the property you already own, one of these is likely to apply:
A NatHERS rating from a recent build
The simplest of the four. If your investment property was built from late 2023 onwards, it was very likely rated 7 stars or higher under NatHERS as part of the current building code. That rating alone is often enough to refinance onto a green rate, using the certificate you should already have from settlement.
A Home Energy Rating for an older property
My favourite, because it's the one most owners of an older property don't know exists. A licensed assessor rates the property as it stands today, no upgrades needed beforehand, and issues a certificate for your lender. Plenty of established investment properties turn out to qualify once they're actually assessed.
A Green Star rating on the building itself
A lovely one when it applies, because it asks nothing extra of you. If your investment property sits in a Green Star certified development, that building-level rating can unlock a green refinance on its own. Worth checking with the body corporate, since it's rarely front and centre in the marketing.
Energy efficient upgrades you've already made
If none of the above apply yet, don't worry. Solar, battery storage, double glazing, EV charging and efficient heating and cooling all count with most lenders, so if you've added any of these since buying, it's worth checking whether your current loan is missing out on a rate you already qualify for.
The rules are tightening for rental properties
This is the part investors tend to overlook. The ACT already requires rental properties to meet insulation standards and disclose their energy rating, Victoria has required efficient fixed heating since 2023 with more standards phasing in from 2027, and NSW is now consulting on its own version. Nothing is locked in everywhere yet, but the direction is consistent, and a property with a strong rating today is already ahead of a compliance curve older stock will eventually have to catch up to.
The asset performs differently
A more efficient rental tends to behave better as an asset, not just as a loan. Lower running costs support occupancy, several lenders offer a higher LVR or reduced LMI on qualifying properties, and efficient homes have consistently held their resale value better. None of this replaces the fundamentals, location and yield still do most of the work, but between two comparable properties, the one that qualifies for green lending is quietly doing more for you across the board.
What's the next step?
A short, friendly call is usually all it takes. Tell me about the property, what's already in place, and your current loan and rate, and I can tell you which of these is likely to apply and roughly what rate you'd be looking at.
Already own an investment property? Let's find out what it qualifies for on a refinance.
Book a free 15-minute call and I'll give you a clear, honest picture of where your current loan stands against a green rate. No pressure, no jargon.
This article contains general information only and does not constitute personal financial or credit advice. NatHERS, Home Energy Rating and Green Star certification requirements, lender eligibility criteria, and product availability are subject to change. Marisa Hoffenberg is a Credit Representative (No. 537544) of Australian Credit Licence No. 393195. Please consider your own circumstances and seek independent advice before making any financial decisions.